Antonio Tejeda Encinas, President of the Euro-American Committee of Digital Law - CEA Digital Law
How is the issuance of crypto-assets regulated? Does regulation apply to every issuance? What are the consequences of an issuance that breaches the rules?
The regulation of crypto-asset issuance varies from one jurisdiction to another: there are bodies of rules that regulate it extensively, but most countries have no specific legislation.
An exception should be made, however, for the issuance of security tokens through an STO (security token offering), which always requires compliance with the relevant regulations. In other words, this type of issuance is already covered by existing legislation in every jurisdiction, even where it is carried out using distributed ledger technology (DLT), in the cases where this is permitted, which is not common.
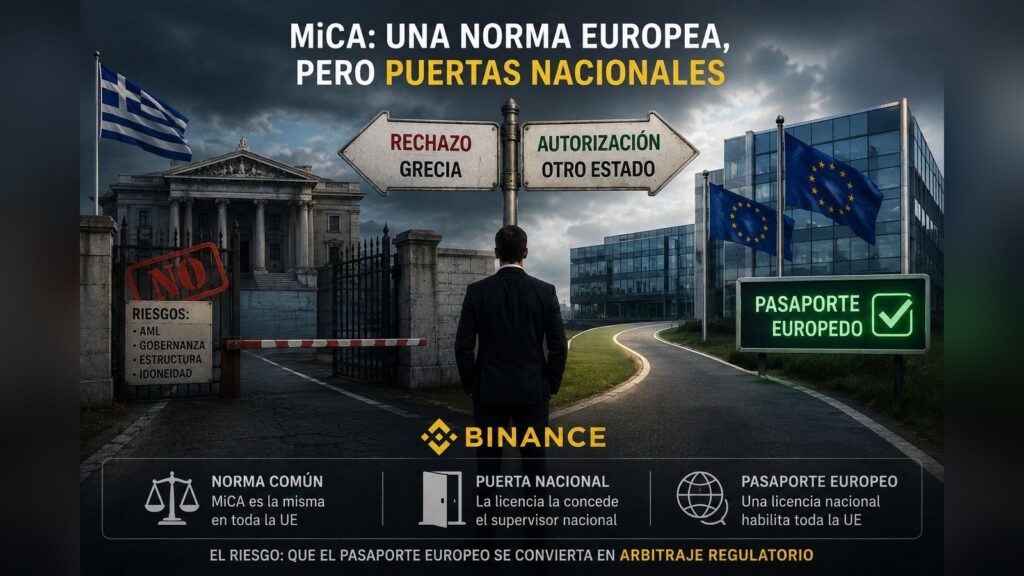
As for crypto-assets that do not qualify as financial instruments, the European Union is a good example of how the picture changes significantly with the Markets in Crypto-Assets Regulation (MiCA). Before it became applicable on 30 December 2024, the only applicable rules were the anti-money laundering (AML) requirements that apply when service providers take part in the offering. Even so, some Member States already have rules governing the advertising of crypto-assets, including issuances (Spain and Belgium, for example).
With MiCA in force, the issuance of crypto-assets falling within the scope of the Regulation (which excludes, among others, security tokens, NFTs and bank deposits) is regulated. Broadly speaking, the legal framework provides as follows for offerings made through ICOs, IEOs or IDOs:
– Stablecoins may only be offered in the European Union with a prior licence; offering them without authorisation is prohibited.
– Issuing e-money tokens requires prior notification rather than a licence, but only credit institutions or electronic money institutions authorised in the EU may issue them. Other entities may, however, offer e-money tokens with the issuer’s authorisation.
– Offering non-monetary crypto-assets does not require a licence or authorisation, but it does require prior notification, accompanied by a white paper containing minimum information and the disclosure of all marketing communications.
– There are certain exemptions from the rules on public offerings, such as issuances aimed exclusively at qualified investors, free offerings, crypto-assets issued as a reward for maintaining the DLT or validating transactions (Bitcoin, for example), and utility tokens for a limited network of providers that have agreements with the issuer.
– If the issuance takes place through an IEO or IDO, the relevant service provider must obtain a prior licence to operate in the European Union, whether as a trading platform, a custodian and/or a placement agent.
All the information above refers to the European Union and is not intended to be exhaustive. For issuances in other jurisdictions, the rules in force in each of them must be analysed.
Newsletter
Events, news and analysis on digital law, straight to your inbox. Only when we have something worth telling you.