Antonio Tejeda Encinas, President of the Euro-American Committee of Digital Law - CEA Digital Law
As the European Central Bank (ECB) recently announced, the preparation phase of the digital euro has been given the green light.
It is worth remembering that the European Parliament is debating the European Commission’s proposal for an EU regulation on the digital euro, which sets out the terms on which it may be issued.
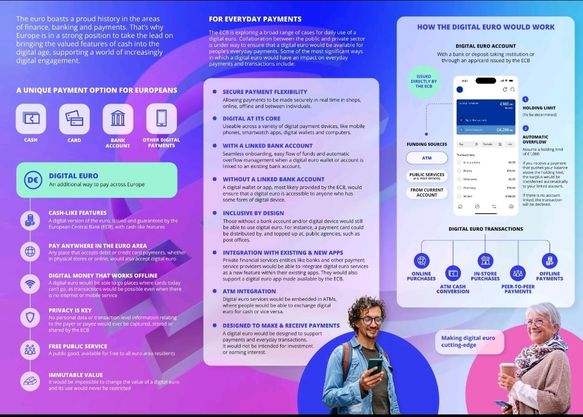
The attached ECB leaflet sheds light on the key features of the digital euro project now under development:
1. It offers a simple option for everyday payments and is compatible with a range of devices, such as smartphones, smartwatches and wallets.
2. It works as a digital option with features similar to cash (without replacing it), enabling real-time P2P payments throughout the euro area, both online and offline (with no internet connection or mobile coverage).
3. It does not require a current account or credit cards. It can be used with or without a linked bank account. In the latter case, a wallet would be used (possibly provided by the ECB). It can even be used without a wallet, with rechargeable prepaid cards.
4. It is offered as a free public service to all residents of the euro area.
5. Its aim is to strengthen the European Union with a public asset backed by the ECB, like cash, providing an alternative to private payment solutions and reducing dependence on non-European means of payment.
6. Issuing it is seen as necessary to keep the euro strong on the global financial stage, in view of threats such as the digital yuan or possible stablecoins from Big Tech.
7. Privacy is regarded as fundamental, and there is a guarantee that the ECB will not collect, store or share personal data from transactions.
8. The digital euro will not be programmable, meaning that its value cannot be altered and its use cannot be restricted. However, banks and payment service providers will be able to integrate services related to the digital euro.
9. It will be possible to use ATMs to exchange digital euros for cash and vice versa.
10. The ECB stresses that the digital euro is designed solely for making payments, not for investment or generating returns. A holding limit will be set, possibly between 3,000 and 4,000 euros per person. If an amount received exceeds this limit, the excess will be transferred to a linked account, if there is one; otherwise, the transaction will be rejected.
Given these features, the digital euro emerges as an alternative to cash, bank deposits, credit cards, payment solutions such as Bizum, and stablecoins: a free, accessible digital means of payment that does not require a current account, with a holding limit designed for small amounts.
Lettre d’information
Événements, actualités et analyses sur le droit numérique, dans votre boîte de réception. Seulement quand il y a quelque chose à dire.